
CPP and Dream Paid $585.8 Million for the One Thing the GTA Is Short of a Tenant.
Five fully leased buildings traded in the same quarter that 85% of newly completed GTA industrial space sat empty. That is not a contradiction. It is the whole trade.
November 5, 2026 · Sunny Gawri, Urban Land Group
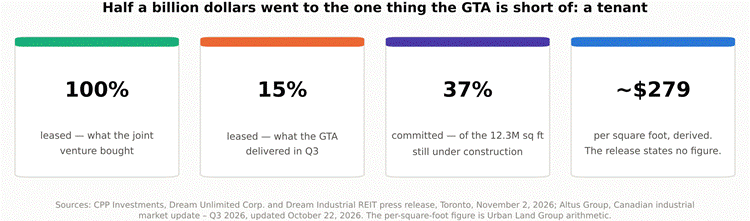
The acquisition against the market it closed into.
What the release actually says
CPP Investments, Dream Unlimited Corp. (TSX: DRM) and Dream Industrial REIT (TSX: DIR.UN) completed the purchase of five GTA logistics assets for $585.8 million — Canadian dollars, which the release states explicitly and at least one international outlet got wrong. The portfolio totals 2.1 million square feet of gross leasable area across four Oshawa properties on Thornton Road and one at 100 Ace Drive in Brampton.
The buildings were built between 2020 and 2024, with 36- to 40-foot clear heights and a loading ratio of one door per 8,000 square feet. They are fully leased. The seller is not disclosed.
The joint venture was formed in December 2025. CPP Investments holds 90%. Including this deal the venture has deployed more than $1.4 billion against a $3 billion target — the release says “nearly half,” which at 47% is fair. For scale, the CPP Fund stood at $863.6 billion at June 30, 2026, so this is a rounding error for CPP and a platform-defining transaction for Dream Industrial, which manages roughly 75.7 million square feet globally.
The market it closed into
Altus Group’s Canadian industrial update for Q3 2026 describes a GTA that is going the other way from the rest of the country.
Nine GTA completions added nearly 2.5 million square feet, of which 85% remained available at quarter-end. Another 12.3 million square feet across 43 projects is under construction, with nearly 63% still available — which Altus attributes to “developers’ continued reliance on speculative projects.” The GTA’s availability rate rose 60 basis points year over year.
Nationally the picture is better: availability of 6.2%, up only 20 bps, and a fifth consecutive quarter of positive net absorption. Calgary tightened 140 bps, Southwestern Ontario 160 bps, Halifax 350 bps. Only the GTA and Montreal loosened. Asking net rents nationally run $15.50 to $16.00 per square foot with what Altus calls “modest downward pressure.”
Altus is blunt about the bifurcation: “uncommitted speculative projects remained less attractive than stabilized assets,” while “legacy assets with functional limitations faced cap-rate expansion and longer lease-up periods.”
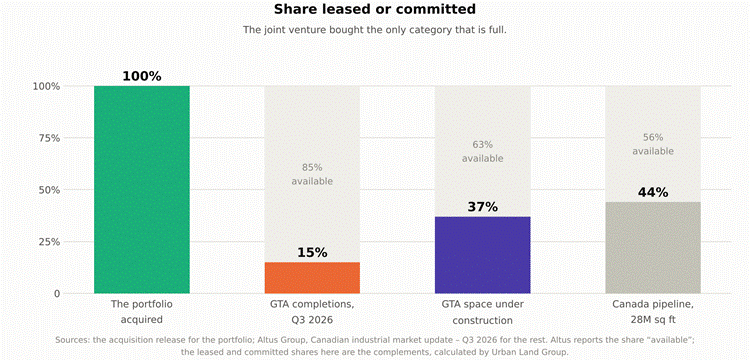
Altus reports the share available; the leased and committed shares are the complements.
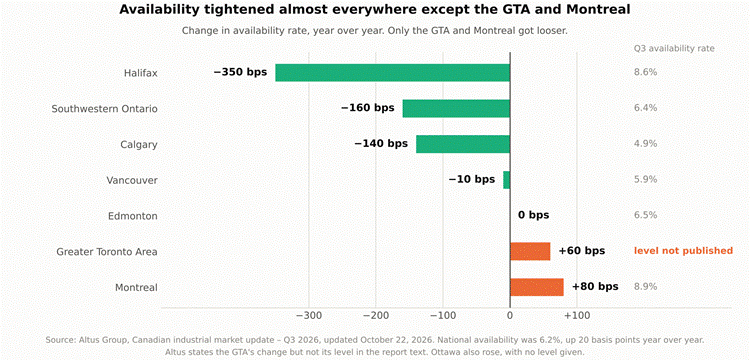
Altus Group Q3 2026. Change in availability rate, year over year.
What they paid, in context
The release publishes no price per square foot. Dividing $585.8 million by 2.1 million square feet gives about $279. The nearest published comparable is Pure Industrial’s purchase of 4670 and 4680 Garrard Road in Whitby from Panattoni — 777,040 square feet for $190.5 million in Q2, which Altus called the largest GTA industrial transaction of that quarter. That works out to about $245 per square foot.
So a larger, newer, fully leased Durham-area portfolio traded roughly 14% higher per square foot two quarters later, in a market where availability rose and asking rents softened. Treat that spread carefully — the assets differ in age, size and tenancy, and neither price per square foot is a disclosed figure. But it is the clearest read available on what stabilised income is worth right now relative to the broader market.
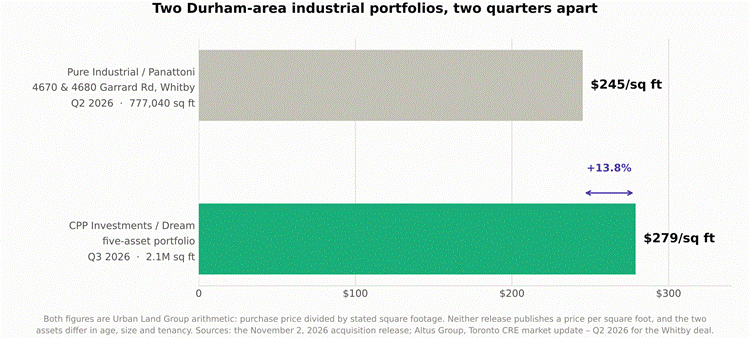
Both figures derived. Neither release publishes a price per square foot.
The assumption buried in the forward-looking statement
The release describes “the opportunity to drive value through executing on embedded mark-to-market rental growth potential.” That is the value-creation thesis: in-place rents are below market, so renewals mark up.
The forward-looking section then lists what that depends on. Among the stated assumptions: “market rents for comparable industrial space in the GTA will remain at or above in-place rents.” The risk factors name “leasing risks, including those associated with the ability to lease vacant space” and “the extent to which market rents exceed in-place rents and the ability to realize mark-to-market rental growth.”
Read that against Altus: GTA availability up 60 bps, 85% of new completions empty, national asking rents under modest downward pressure. The disclosure is doing its job — it is telling you precisely which variable the upside rests on, and that variable is currently moving the wrong way. None of which makes the acquisition wrong. The in-place income is contracted; the mark-to-market is the option, and the option is the part that is exposed.
Where the coverage drifted from the source
Four small things worth getting right before any of this is repeated to a client.

Each item checked against the primary release and the Altus report.
| THE ULG VIEW The trade here is not a bet on the GTA industrial market. It is a bet against lease-up risk. Ninety per cent of the equity is a pension fund buying contracted income in a market where 85% of brand-new space has no tenant. Those two facts are the same decision viewed from opposite ends. For anyone underwriting industrial land or a speculative build, that is the signal. Institutional capital is pricing a premium for the absence of leasing risk and discounting everything that carries it. Altus says it plainly: uncommitted speculative projects are less attractive than stabilized assets. If a pro forma assumes a spec building leases on completion at asking rents, the market just told you what it thinks of that assumption. The 12.3 million square feet under construction is the number to watch, not the 2.5 million delivered. Sixty-three per cent of it is still available, and it arrives over the next several quarters into a market whose availability is already rising. Lease-up periods and free-rent packages are the variables that move, not headline asking rents. Price the mark-to-market separately from the income. CPP and Dream disclosed exactly the right caveat: the rental growth upside assumes GTA market rents stay at or above in-place rents. On an acquisition underwrite, run the case where they do not, and see whether the deal still works on in-place income alone. If it does, you are buying a bond with an option attached. If it does not, you are buying the option. Durham is where this is concentrated and that is not an accident. Four of the five assets are on Thornton Road in Oshawa, the Q2 benchmark was in Whitby, and Amazon bought a 92-acre Oshawa land assembly from Broccolini earlier this year for nearly $124 million. Eastern GTA 400-series-adjacent land with servicing is attracting large-format demand while the broader market softens. That is a sub-market story worth tracking on its own. |
| WHAT IS CONFIRMED AND WHAT IS NOT Confirmed from the primary release. The $585.8 million price and that it is in Canadian dollars; 2.1 million square feet of GLA; five assets built between 2020 and 2024 with 36- to 40-foot clear heights and a one-door-per-8,000-square-foot loading ratio; fully leased status with no tenants named; CPP Investments’ 90% stake; the December 2025 formation, $3 billion target and more than $1.4 billion deployed; the undisclosed seller; both quotes and both titles; the $863.6 billion CPP Fund and Dream’s $28 billion AUM; and every forward-looking assumption quoted. Source: the Business Wire release carrying the CPP Investments, Dream Unlimited and Dream Industrial REIT joint announcement, Toronto, November 2, 2026. Confirmed from Altus Group. The 2.5 million square feet of GTA Q3 completions and the 85% available; the 12.3 million square feet across 43 projects and the 63% available; the 60-basis-point rise in GTA availability; national availability of 6.2% up 20 bps; the regional availability figures; the $15.50 to $16.00 national asking rent range; and the fifth consecutive quarter of positive national net absorption. Source: Canadian industrial market update – Q3 2026, updated October 22, 2026. Derived, not disclosed. The ~$279 and ~$245 per square foot figures, the 14% spread, the 47% share of the $3 billion target, and the leased and committed percentages shown in the exhibits. All are simple arithmetic on published figures, and all are labelled as such. Not in the release. Tenant names, any lease expansion, any cap rate, yield or NOI, the price per square foot, and the individual size or clear height of any single building. The release gives the addresses only in photo captions. Not verified. The Altus report’s GTA availability level — the text gives the change but not the rate, which appears only in an unreadable chart. The Connect CRE article underlying the 85% figure could not be retrieved; the figure was confirmed directly from Altus instead. Altus and Dream are private and public market participants respectively, not official statistical agencies. This is market commentary prepared for discussion. Not investment advice, and not an Opinion of Value for any property. |
Sources
PRIMARY SOURCES
· CPP Investments, Dream Unlimited Corp. and Dream Industrial REIT — CPP Investments and Dream Complete $585.8 Million Acquisition of GTA Industrial Portfolio. Toronto, November 2, 2026. Source of every deal figure and both quotes. https://www.businesswire.com/news/home/20261102913568/en/CPP-Investments-and-Dream-Complete-$585.8-Million-Acquisition-of-GTA-Industrial-Portfolio
· Dream Industrial REIT and Dream Unlimited Corp. continuous disclosure, including annual information forms and MD&A, filed on SEDAR+. https://www.sedarplus.ca
· CPP Investments — corporate newsroom. https://www.cppinvestments.com/newsroom/
PRIVATE RESEARCH — NOT OFFICIAL
· Altus Group — Canadian industrial market update, Q3 2026. Updated October 22, 2026. Jennifer Nhieu, Senior Research Analyst. Source of all availability, completion and pipeline figures. https://www.altusgroup.com/insights/canadian-industrial-market-update-q3-2026/
· Altus Group — Toronto commercial real estate market update, Q2 2026. Updated August 4, 2026. Source of the Whitby comparable and the Q2 GTA industrial investment volume. https://www.altusgroup.com/insights/toronto-commercial-real-estate-market-update-q2-2026/
· Connect CRE Canada — CPP, Dream Acquire Five GTA Industrial Properties For $586M, and 85% Of New GTA Industrial Space Remains Unleased. The items that prompted this note. https://www.connectcre.ca/stories/cpp-dream-acquire-five-gta-industrial-properties-for-586m/
Urban Land Group · Land development advisory and commercial real estate · 30 Eglinton Avenue West, Mississauga, Ontario
Sunny Gawri is a registered real estate sales representative with Royal LePage Signature. Market commentary prepared for discussion. Not investment advice, and not an Opinion of Value for any specific property.